In July 2023, the Office of Management & Budget published an update to “Core Based Statistical Areas, Metropolitan Divisions, and Combined Statistical Areas”. That document contains the latest definitions of Metropolitan Statistical Areas or “MSAs’) which play a big role in CRA Assessment Area delineation. The […]
Read more →
There has been much understandable handwringing about the new CRA and its complexity as well as the high CRA exam failure rate predicted by regulators based on the new assessment areas and the higher performance standards embedded in the new rule. But there is a greater […]
Read more →
I’ve written at least a dozen articles about the dramatic impact the new CRA is going to have on banks. Until now, only about 1.2% of bank CRA examinations end with a failing grade. But, by the estimates of the regulators, if the new rule had […]
Read more →
How will loan data collection change given the pause on the 1071 rule? If that’s not a topic for today, where can I find a good source for information regarding loan data collection? I would not make any changes until the Court rules on the 1071 […]
Read more →
Our office has been inundated with inquiries about an aspect of the impact of the impending new CRA rule. As we have noted in previous articles there are mistakes and inconsistencies in the new CRA Rule, and some of these mistakes and inconsistencies will have immediate […]
Read more →
As I write this article the Department of Justice is pursuing a record-breaking number of “redlining” cases against banks and mortgage lenders. The “Anti-redlining Initiative” was announced October 22, 2021, by Attorney General, Merrick Garland. In his press release AG Garland stated, “We know full well […]
Read more →
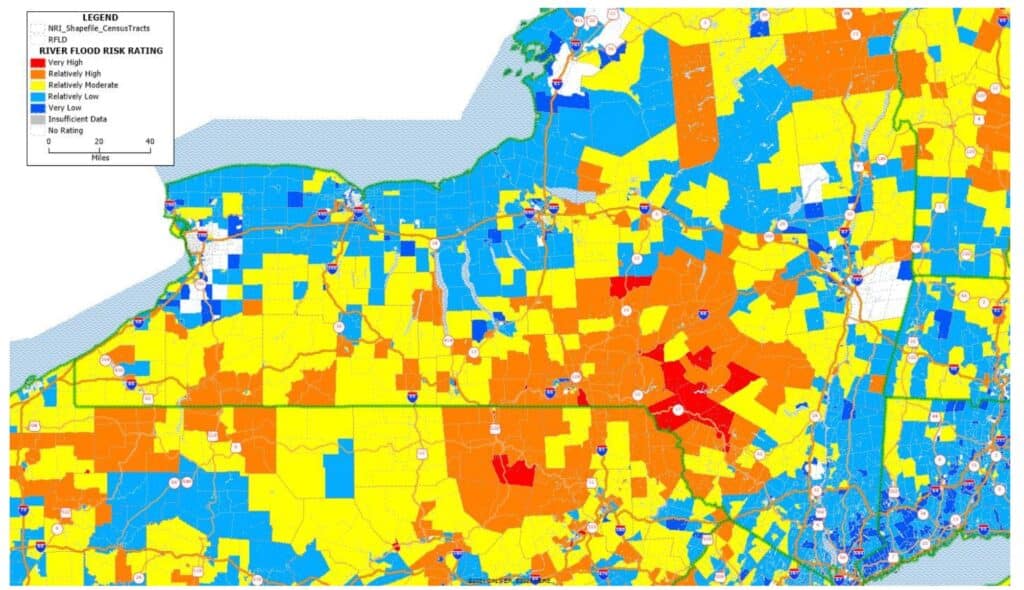
Climate Risk Assessments for banking purposes are in the early stages of development. No laws or regulations have been issued regarding the topic. Nonetheless, it is obvious that lawmakers and regulators are keenly intent on developing laws and regulations to require banks to develop climate-related risk […]
Read more →
2022 CRA data released by the FFIEC December 2023 Ordered Alphabetically by State One of the most important CRA responsibilities for Intermediate-Small Banks and Large Banks is “Community Development Lending”. But while Community Development Lending is critically important, there is very little information available about the […]
Read more →
The new CRA Rule has a number of surprises for banks and maybe a surprise or two for the regulators themselves. One of those surprises involves the transition rules in §__.51 as they pertain to the April 1, 2024, the effective date of the new rule, […]
Read more →
Most of the articles published about the new CRA rule have repeated the party line – that the new rule “modernizes” the Regulation, that it will make CRA exams more objective and CRA ratings more consistent, etc. But the new CRA has a very serious, if […]
Read more →
Dear Banker, The new CRA Rule contains a “break” for Large banks that would exempt them from having to declare Retail Lending Assessment Areas (“RLAAs”) for any calendar year in which the bank lends more than 80% of its home mortgages, multifamily loans, small business loans, […]
Read more →
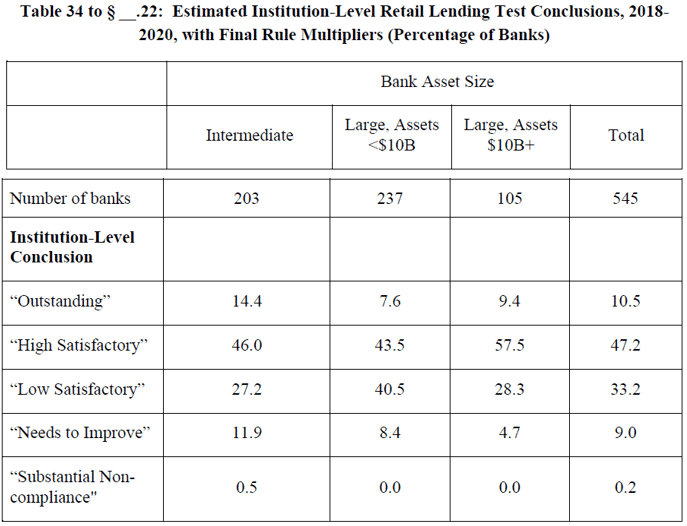
In Parts I and II I explained the devastating impact of the new CRA Rule and what the underlying reasons for that adverse impact are. In Part III I will touch upon what banks are most significantly impacted by the new Rule. If you are wondering […]
Read more →
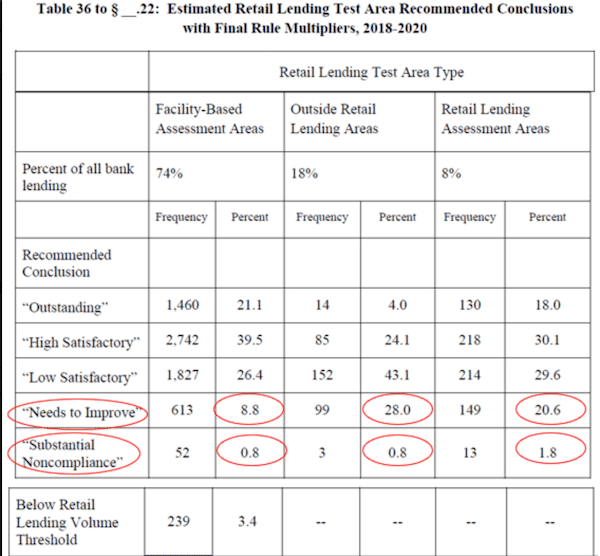
In my previous email I explained the devastating impact of the new CRA Rule on the percentage of banks receiving a less than satisfactory CRA Performance Rating. The data in Table 32 within the new Rule demonstrate that if the Rule had been applied from 2018-2020 […]
Read more →
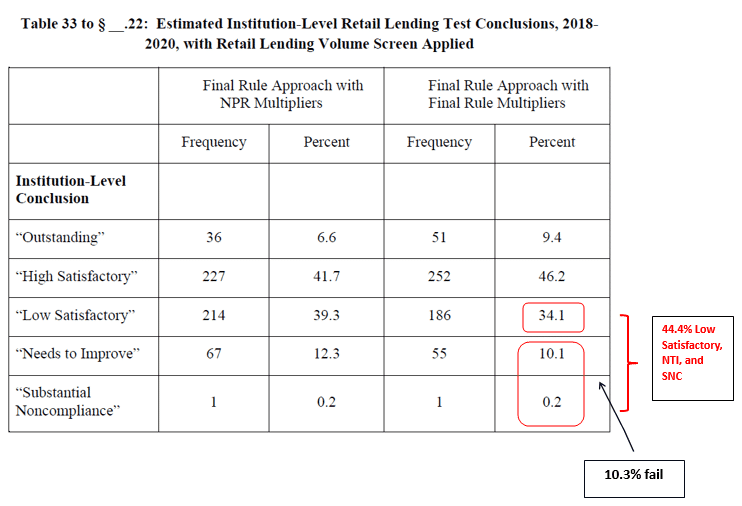
With all the news stories circulating about the new CRA Rule, it’s surprising that not one article has addressed the topic that should be the biggest story of all – the catastrophic implications for banks! What I am referring to is the dramatic increase in the […]
Read more →
To determine the size of the small business do we include the entire relationship or just the information for the individual loan? It would be based on the GAR of the borrower and affiliates if borrower elects to provide that information (but it is not required, […]
Read more →
Will CRA Large Banks still need to report their loan data after this regulation take effect? It is reporting small business image likely that CRA reporting would continue during the transition period. But after that (beginning in 2026) small business and small farm loans under CRA […]
Read more →
Do loan applications and originations for natural persons (individual, DBA, or sole proprietorship) count as a covered application or covered transaction?
Read more →
I do regulatory reporting for a bank as well as their loan loss reserve. Will this affect the allowance calculation?I do regulatory reporting for a bank as well as their loan loss reserve. Will this affect the allowance calculation? No. Suggestions for risks to include in […]
Read more →
The definition of a small business loan based on revenues and loan size. And how does that differ from the definition of a CRA small business loan? Thank you. Loan size will not be relevant under 1071 unlike CRA where it is determinative. Under CRA you […]
Read more →
If the owners of a minority owned business are not minority individuals, then how do we define a minority owned business? The key to your question is to understand that the Bureau has introduced “control” as an alternative to ownership. They define control on page 817 […]
Read more →